Gibraltar, Isle of Man, Alderney: Three Jurisdictions, Three Strategies
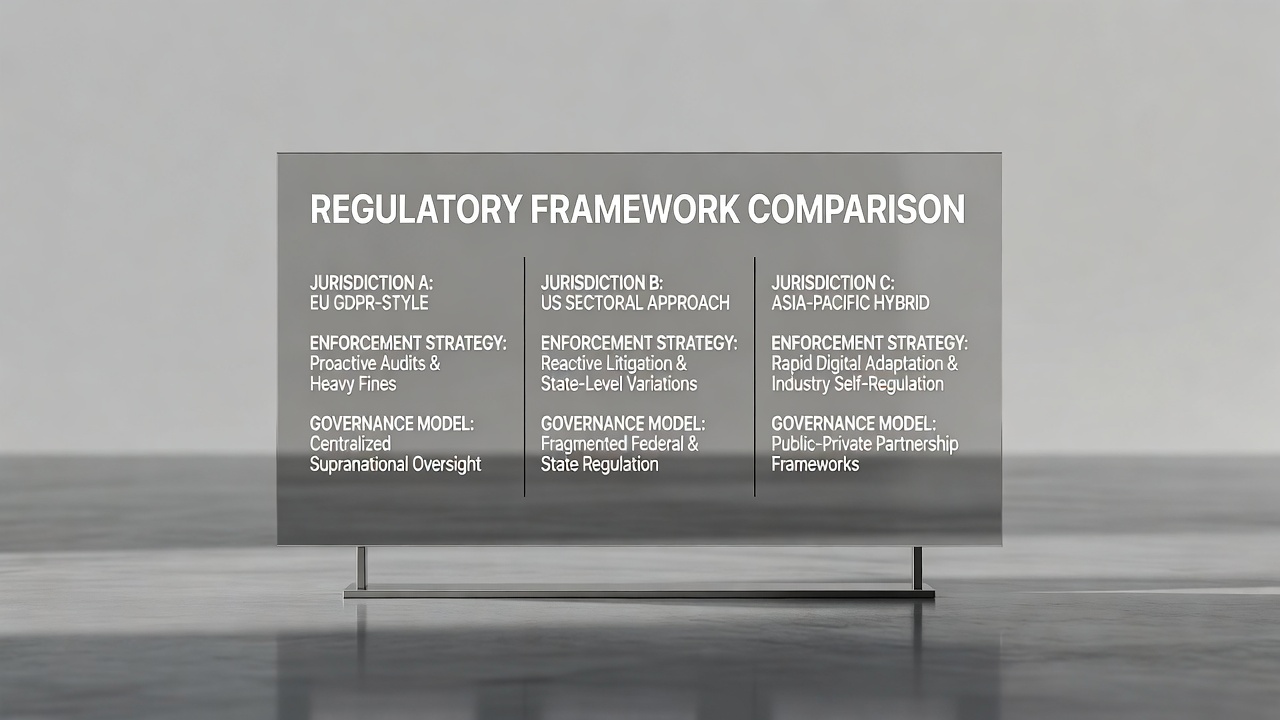
Three small jurisdictions have become the backbone of European online gambling regulation. Their approaches differ sharply. The implications are significant.
Rizz Cash Tape3 min read
The Gambling Commission of Gibraltar issued its first licences in 1998. The jurisdiction saw an opportunity: Europe needed somewhere to operate online casinos. The regulatory infrastructure was minimal. The tax rate was reasonable. Gibraltar accepted the business.
By 2024, Gibraltar hosts approximately 300 licensed gambling operators. The jurisdiction generated £1.2 billion in tax revenue in 2022. This is a small territory with 30,000 residents. The concentration of gambling licensing has transformed the economy entirely.
Gibraltar's Approach
Gibraltar's strategy was simple: be permissive but competent. Accept licences from operators. Require them to meet basic standards around responsible gambling and player protection. Do not interfere too heavily. This created an attractive jurisdiction for operators who wanted licensing without excessive regulation.
The regulator, the Gibraltar Gambling Commissioner, operates with a light touch. Operators are required to hold player funds in segregated accounts. They must have KYC procedures. But there is minimal ongoing oversight. A casino licensed in Gibraltar can operate globally (excepting jurisdictions where online gambling is explicitly banned) without daily regulatory interference.
This made Gibraltar the European standard for years.
Isle of Man's Distinction
The Isle of Man, a British Crown Dependency, took a different approach. Where Gibraltar was permissive, the Isle of Man was cautious. The Gambling Supervision Commission, established in 2010, imposed stricter requirements. Background checks were more rigorous. Responsible gambling controls were mandatory. The Isle of Man regulator was willing to reject applicants.
The trade-off was immediate. Fewer operators chose the Isle of Man because the process was slower and more expensive. But those who obtained licences did so with enhanced legitimacy. The label 'licensed by the Isle of Man' meant something. It meant the operator had passed a genuine regulatory gauntlet.
Operators began to dual-license: Gibraltar for European coverage, Isle of Man for credibility with the most risk-averse players.
Alderney's Miscalculation
Alderney, another small jurisdiction, tried to enter the market. They offered low tax rates and fast licensing. For about ten years, this worked. Operators chose Alderney. Tax revenue flowed in.
Then the strategy failed. Alderney became associated with less-reputable operators. The regulatory brand eroded. When fraud cases emerged involving Alderney-licensed operators, the jurisdiction's reputation collapsed. By 2018, most serious operators had shifted to Gibraltar or the Isle of Man. Alderney's share of the European market contracted sharply.
The Regulatory Convergence
Since 2020, the trend has been convergence. The UK established its own online gambling regulator. The European Union moved toward harmonisation. Jurisdictions that had differentiated themselves through permissiveness faced pressure to increase standards. Alderney has slowly rebuilt. Gibraltar has raised requirements. The Isle of Man, having started strict, has seen less need to change.
The Practical Difference
From a player's perspective, the differences are subtle. A casino licensed in Gibraltar, the Isle of Man, or Malta is probably safe. Your account is probably segregated. You probably have recourse if something goes wrong.
The differences matter more to operators. A low-cost Alderney licence is cheaper than a rigorous Isle of Man licence. A high-volume Gibraltar approach requires less vetting than an Isle of Man approach. These operational differences add up. They affect the type of operator who chooses each jurisdiction and the standard of service that follows.
The Future
The three jurisdictions will likely converge further. Global regulation is moving toward minimum standards that even permissive regulators cannot undercut. Alderney will either match these standards or lose market share. The days of substantive regulatory arbitrage are ending.
What persists is the brand. Operators who positioned themselves as rigorous will maintain that positioning. Those positioned as cost-optimised will maintain that. The underlying regulatory differences, once dramatic, have narrowed. The perception of difference lingers longer than the difference itself.